The Pier: Investor Corner
The PIER Home
Frequently Asked Questions
Financial Counselors
Resource Center
Caught in Between: Supporting Parents and Children
If you’re supporting both aging parents and growing children, you’re part of what’s often called the sandwich generation. According to a study by Pew Research Center, about 23% of adults in the United States are part of the sandwich generation. It’s a role that can bring meaning, but also real emotional, financial, and logistical pressure.
Alongside caregiving responsibilities, career demands, and long-term planning, many are navigating tough conversations about health, finances, and independence, often feeling pulled in every direction at once. The good news? There are ways to make this more manageable. Start by organizing what you can. Create a clear view of finances, including caregiving costs, insurance coverage, and long-term needs.
Even small steps can reduce uncertainty. Then focus on your communication. Talk openly with family about expectations, roles, and financial realities so decisions aren’t made in a crisis. Look for support, whether that’s workplace benefits, community programs, or professional advice. Delegating and sharing responsibilities can ease the burden.
And don’t forget yourself. Building in flexibility financially and emotionally can help you stay resilient during a demanding season of life. Being caught in the in-between isn’t easy, but with planning, communication, and support, it’s possible to care for others while still protecting your own future. And while this season can feel overwhelming, it can also be a meaningful time of connection and an opportunity to take steps toward a more secure future for those you care about.
To watch the full video provided by CAPTRUST at Work, click here.
Is your investment mix still working for you?
Your investment mix should change as retirement gets closer. Here’s how to tell whether your current allocation still fits your timeline—and what to do if it doesn’t.
If you set up your retirement investments years ago and haven’t looked closely since, you’re not alone. Many people choose a mix of stocks and bonds in their 30s or 40s, while some never select their investments at all and use a default option—just assuming it will carry them all the way through retirement.
But here’s the reality: Your investment mix isn’t something you set once and forget. As you get closer to retirement, what worked before can start working against you.
A shift happens—sometimes slowly, sometimes all at once—where your priorities change. You move from building wealth to protecting it. And that shift should be reflected in how your investments are structured
When you’re younger, your main goal is growth. You have time on your side. If the market drops, you can wait it out, keep contributing, and benefit from the eventual recovery.
That’s why a higher stock allocation—sometimes 70%, 80%, or more—often makes sense in your 30s and 40s. But by the time you reach your late 50s or early 60s, the situation changes in a few key ways:
- You have less time to recover from market downturns.
- You’re closer to needing income from your investments, which means large losses can have a lasting impact on your plans in a way they simply couldn’t earlier in your career.
This is where risk tolerance can become misleading. You may still feel comfortable with risk—but your financial situation may not support the same level of exposure.
Click here to review TIAA’s full article, Is Your Investment Mix Still Working for You?
Engagement Corner
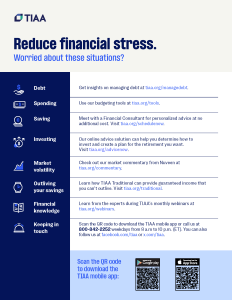
TIAA: Help boost your financial know-how with TIAA’s live webinars — see the flyer below for topics and dates. To see currently scheduled live webinars or previously recorded on-demand webinars, visit www.tiaa.org/webinars2025.
|
October 14th @ 12pm ET: Decoding AI, Interest Rates, and the Midterm Wildcard – Q4’s Big Three |
October 21st @ 11am ET: What is an annuity? Know the basics |
|
November 12th @ 11am ET: How to get the most from your employee retirement plan |
November 24th @ 12pm ET: Myth Busting: Planning and Managing Healthcare Expenses |